
Chapter 7 Bankruptcy: How It Works, Who Qualifies and What It Costs
Last updated 11/03/2026 by
SuperMoney Team
Edited by
Andrew Latham
Summary:
Chapter 7 bankruptcy wipes out most unsecured debt, like credit cards, medical bills and personal loans, in about four months. You qualify if your income is below your state’s median or you pass the means test, and the court fee is $338 (you can pay in installments or ask for a waiver). Most filers keep everything they own: more than 95% of cases are “no asset” cases where the trustee sells nothing. The tradeoff is a bankruptcy on your credit report for up to 10 years, and some debts, like child support, recent taxes and most student loans, survive.
If you’re reading this, money has probably been keeping you up at night. Maybe the minimum payments now eat most of your paycheck, or a collector just filed a lawsuit. You’re not alone, and you’re not out of options. In the 12 months ending September 30, 2026, Americans filed 375,784 personal Chapter 7 cases, up 13.5% from the year before.
Chapter 7 is the fastest and cheapest way to get a legal fresh start. It’s also not right for everyone. Here’s exactly how it works, who qualifies, what it costs, what you keep and what happens to your credit, with real numbers at every step so you can decide with a clear head.
What is Chapter 7 bankruptcy?
Chapter 7 is a type of bankruptcy under Title 11 of the U.S. Code that cancels (discharges) most of your unsecured debts. It’s also called “liquidation” or “straight” bankruptcy, because a court-appointed trustee can sell property that isn’t protected by law and use the money to pay your creditors.
That word “liquidation” scares people more than it should. Every state protects a set of basic property, called exemptions, and for most filers those exemptions cover everything they own. The U.S. Trustee Program, the Justice Department office that oversees bankruptcy cases, says more than 95% of Chapter 7 cases end up as no-asset cases. In other words, nothing gets sold, and creditors get nothing from the trustee.
Chapter 7 is by far the most common choice for individuals. In fiscal year 2026, it made up about 63% of all personal bankruptcy filings. The other main option for individuals is Chapter 13 bankruptcy, a three- to five-year repayment plan.
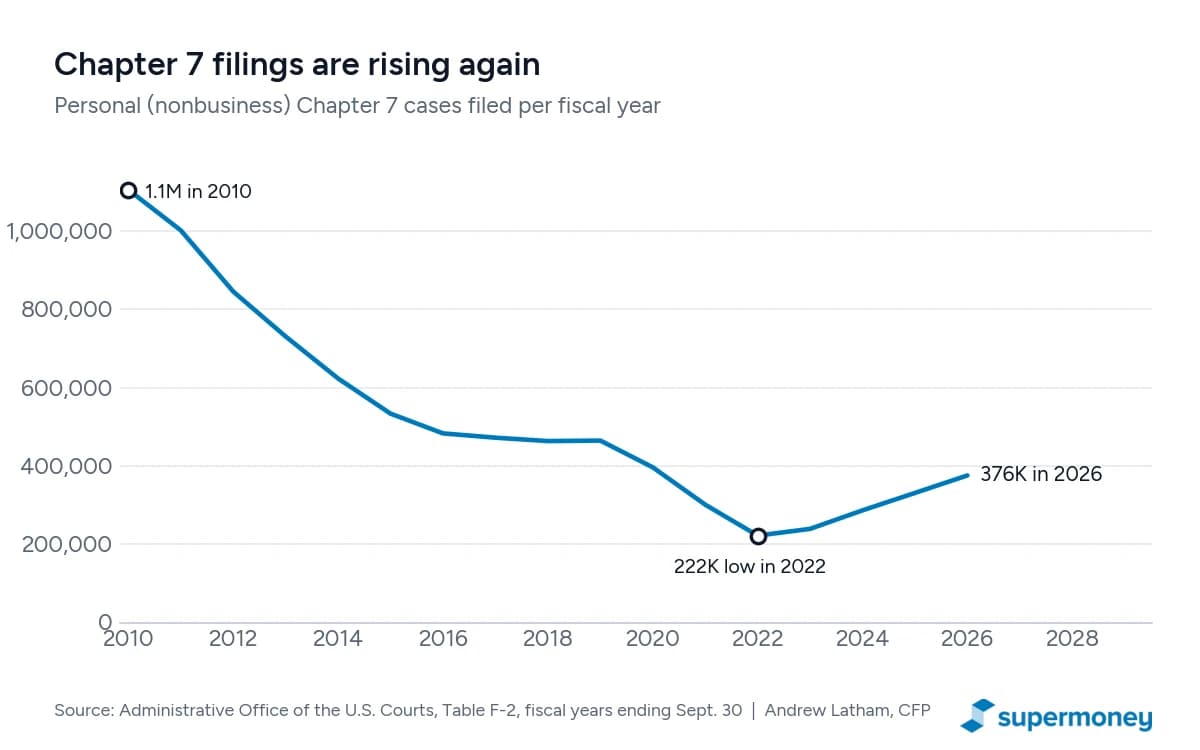
Filings are climbing again after hitting a low in 2022, when pandemic relief money and paused student loan payments kept many households afloat. Even after four straight years of increases, they’re still about 66% below the 2010 peak.
How Chapter 7 works, step by step
Most Chapter 7 cases follow the same path. From the day you file to the day your debts are discharged usually takes about three to four and a half months.
| Step | When it happens | What you do |
|---|---|---|
| 1. Credit counseling | Within 180 days before you file | Take a short budget briefing from a provider approved by the U.S. Trustee Program, online or by phone. Keep the certificate. |
| 2. File your petition | Day 1 | File the petition, schedules of what you own and owe, your income and expenses, and the means test form. Pay the fee or ask for installments or a waiver. |
| 3. Automatic stay starts | Day 1 | Collection calls, lawsuits, wage garnishments and most foreclosures stop right away. |
| 4. Meeting of creditors (341 meeting) | 21 to 40 days after filing | Answer the trustee’s questions under oath. It usually takes 10 minutes or less, and creditors rarely show up. |
| 5. Debtor education course | Within 60 days after the 341 meeting date | Take a second short course on personal finance and file the certificate. No certificate, no discharge. |
| 6. Objection deadline | 60 days after the 341 meeting date | Creditors and the trustee must object to your discharge, or to discharging a specific debt, by this date. |
| 7. Discharge | Usually 60 to 90 days after the 341 meeting date | The court issues your discharge order. Your case closes soon after. |
The automatic stay
The moment you file, a court order called the automatic stay protects you. Creditors have to stop calling, suing, garnishing your wages and repossessing property while your case is open. For many people, this is the first quiet week they’ve had in months.
There’s one catch for repeat filers. If you had a bankruptcy case dismissed in the past year, the stay ends after 30 days unless the court extends it. If you had two or more cases dismissed in the past year, there’s no automatic stay at all unless you ask the court for one.
The trustee and the 341 meeting
When you file, the court assigns a trustee to your case. The trustee’s job is to review your paperwork, look for property that isn’t exempt and check for fraud. At the 341 meeting, named after Section 341 of the bankruptcy code, the trustee will confirm your identity and ask questions like “Did you list all your assets?” and “Have you transferred property to anyone in the last two years?” A judge isn’t there. Bring your photo ID and proof of your Social Security number, and answer honestly.
Do you qualify? The Chapter 7 means test
Congress added the means test in 2005 to steer people who can afford to repay some of their debt into Chapter 13. It has two steps, and most people only need the first one.
Step 1: Compare your income to your state’s median
Add up your household’s gross income from the six full calendar months before you file, divide by six, and multiply by 12. If that number is at or below the median income for a household your size in your state, you pass. You don’t have to do anything more.
Here are the medians the U.S. Trustee Program uses for cases filed on or after July 15, 2026. For households larger than four, add $11,100 per person.
| State | 1 person | 2 people | 3 people | 4 people |
|---|---|---|---|---|
| California | $79,253 | $102,797 | $116,541 | $139,071 |
| Texas | $66,837 | $86,714 | $99,273 | $117,962 |
| Florida | $69,876 | $86,523 | $97,540 | $114,761 |
| New York | $73,272 | $92,902 | $115,579 | $139,040 |
| Pennsylvania | $72,230 | $87,534 | $110,151 | $135,862 |
| Illinois | $73,180 | $93,934 | $113,625 | $137,902 |
| Ohio | $66,239 | $83,725 | $102,504 | $123,702 |
| Georgia | $68,478 | $84,965 | $101,479 | $123,481 |
| North Carolina | $67,117 | $84,384 | $101,535 | $116,737 |
| Michigan | $67,352 | $83,432 | $103,449 | $123,010 |
Other states are listed on the U.S. Trustee Program’s means testing page. The figures change a few times a year, so check the table that applies to your filing date.
Example: Jasmine is a single mom with two kids in Houston. Over the last six months, she grossed $28,800, or $4,800 a month. Annualized, that’s $57,600, well under the $99,273 median for a three-person household in Texas. She passes the means test at step 1.
Step 2: If you’re above the median, the disposable income test
If your income is above the median, you fill out a second form (Official Form 122A-2). It subtracts allowed living expenses, which mostly come from IRS spending standards, plus your actual payments on things like your mortgage, car loan, taxes, health insurance and child support. What’s left is your monthly disposable income. Multiply it by 60 (five years of payments) and compare it to these thresholds:
| Disposable income over 60 months | Result |
|---|---|
| Less than $10,275 (under $171.25 a month) | You pass. No presumption of abuse. |
| $17,150 or more ($285.84 a month or more) | Abuse is presumed. You’ll likely need Chapter 13 unless you can show special circumstances, like a serious medical condition or active military duty. |
| $10,275 to $17,149 | Abuse is presumed only if that amount would repay at least 25% of your unsecured debt that isn’t a priority debt (like credit cards and medical bills). |
Example: The Garcias are a family of four in Columbus, Ohio, earning $11,200 a month, or $134,400 a year. That’s above Ohio’s $123,702 median, so they complete step 2. After allowed expenses, their mortgage and two car payments, they have $230 a month left, or $13,800 over 60 months. That’s in the middle zone. If they owe $40,000 in credit card debt, $13,800 would repay more than 25% of it, so abuse is presumed. If they owe $80,000, 25% is $20,000, and $13,800 doesn’t reach it, so they pass.
The means test forms are detailed, and small mistakes can change the result. If you’re near the line, it’s worth paying a bankruptcy attorney to run the numbers.
Other eligibility rules
- Credit counseling: You must complete it within 180 days before filing.
- No recent Chapter 7 discharge: You can’t get a Chapter 7 discharge if you filed a Chapter 7 case that ended in a discharge within the past eight years.
- No recent Chapter 13 discharge: The wait is six years after filing a Chapter 13 case that ended in a discharge, unless your plan paid all of your unsecured debt, or at least 70% of it in a good-faith plan.
- Honesty: Hiding assets, lying on your forms or moving property to family before filing can get your discharge denied and can be a federal crime.
How much does Chapter 7 cost?
| Cost | Amount | Notes |
|---|---|---|
| Court filing fee | $338 | $245 filing fee + $78 administrative fee + $15 trustee fee |
| Credit counseling course | Varies, often under $50 | Approved providers must offer reduced or free services if you can’t pay |
| Debtor education course | Varies, often under $50 | Same fee-waiver rule as credit counseling |
| Attorney | Varies by market | Usually a flat fee paid before filing. Many lawyers offer free consultations, so get two or three quotes. |
Attorney fees are the biggest variable. A Government Accountability Office (GAO) study found the average Chapter 7 attorney fee was $1,078 back in 2007, and fees have risen since. A simple case with no house, steady W-2 income and no business usually costs less than one with real estate, self-employment income or a pending lawsuit.
How to file Chapter 7 with no money
Being broke is often the reason you need bankruptcy, and the system has a few ways around the cost:
- Pay the court fee in installments. You can ask to split the $338 into up to four payments, all paid within 120 days of filing (the court can stretch that to 180 days).
- Ask for a fee waiver. If your household income is below 150% of the federal poverty guidelines and you can’t afford installments, you can ask the court to waive the fee entirely on Official Form 103B.
- Look for free legal help. Legal aid offices, law school clinics and local bar association pro bono programs handle bankruptcy cases for low-income filers. The court’s website for your district usually lists them.
- Use a nonprofit filing tool. Some nonprofits help people with simple cases prepare their forms for free.
Filing with or without a lawyer
You can file on your own, which is called filing “pro se.” It saves the attorney fee, but the risk is real: a missed form, a wrong exemption or an asset you forgot to list can get your case dismissed or cost you property you could have kept. Federal courts strongly recommend hiring an attorney. If your case is simple, you’re below the median and you own little, filing yourself can work. If you own a home, have a car loan you want to keep, run a business or face a lawsuit, hire a lawyer.
What debts Chapter 7 erases, and what survives
| Usually wiped out | Usually survives |
|---|---|
| Credit card debt | Child support and alimony |
| Medical bills | Most recent income taxes, and taxes for returns never filed or filed late within the past two years |
| Personal loans and payday loans | Student loans, unless you prove undue hardship |
| Past-due rent and utility bills | Court fines, penalties and restitution |
| Collection accounts and most court judgments | Debts from fraud, drunk driving injuries or willful harm |
| Old income taxes that meet the 3-2-240 rules below | Loans from your own 401(k) |
| The balance left after a repossession or foreclosure | Liens: your mortgage and car lender can still take the property if you stop paying |
A few traps to know about:
- Recent luxury charges and cash advances. Charges over $900 for luxury goods with one creditor in the 90 days before filing, or cash advances over $1,250 in the 70 days before filing, are presumed to be fraud. Don’t run up your cards before you file.
- Old income taxes can go away. Federal income tax can be discharged if the return was due (including extensions) more than three years ago, you filed it more than two years ago, the IRS assessed it more than 240 days ago, and there was no fraud. Our guide to clearing tax debt in bankruptcy walks through the details.
- Student loans are hard but no longer hopeless. You have to file a separate lawsuit inside your case, called an adversary proceeding, and show undue hardship. Since November 2022, the Justice Department has used a simpler attestation form for federal student loans. From November 2022 through March 2024, 99% of the decided cases that used it got full or partial relief.
What you keep: exemptions
Exemptions decide what’s protected from the trustee. Your state sets them, and about 19 states plus Washington, D.C., including Texas, New York, Pennsylvania and Michigan, let you pick the federal list instead. You have to choose one set, not mix them. To use a state’s exemptions, you generally must have lived there for the 730 days (two years) before filing.
Here are the federal exemptions for cases filed from April 1, 2025, through March 31, 2028. They double for married couples filing together.
| Property | Federal exemption |
|---|---|
| Home equity (homestead) | $31,575 |
| One vehicle | $5,025 of equity |
| Household goods and clothing | $800 per item, $16,850 total |
| Jewelry | $2,125 |
| Wildcard (any property) | $1,675, plus up to $15,800 of any unused homestead amount |
| Tools of your trade | $3,175 |
| 401(k)s and pensions | Fully protected |
| IRAs | Up to $1,711,975 |
| Social Security, unemployment and public benefits | Fully protected |
State exemptions can be much more generous, especially for homes:
| State | Home equity | Vehicle |
|---|---|---|
| Texas | Unlimited value, up to 10 acres in a city or 100 to 200 acres in the country | One vehicle per licensed household member, within a $50,000 (single) or $100,000 (family) personal property cap |
| Florida | Unlimited value, up to half an acre in a city or 160 acres outside one | $5,000 |
| California | System 1: $300,000 to $600,000, depending on county home prices. System 2: $36,750 | $8,625 in either system |
| New York | $102,400 to $204,825, depending on county | $5,500 |
One limit applies everywhere: if you bought your home within about 3.3 years (1,215 days) before filing, the state homestead exemption is capped at $214,000, even in unlimited states like Texas and Florida.
Can I keep my car?
Usually, yes. If your car is paid off and your equity fits under your vehicle exemption (plus any wildcard), it’s protected. If you have a car loan, you have three choices, and you need to make them within 45 days after your 341 meeting:
- Reaffirm the loan. You sign an agreement to keep paying, and the loan survives bankruptcy. You keep the car, but you’re on the hook again if you default later. You can cancel a reaffirmation within 60 days after it’s filed with the court or before your discharge, whichever is later.
- Redeem the car. You pay the lender what the car is worth today in one lump sum, even if you owe more. If you owe $11,000 on a car worth $6,000, you could redeem it for $6,000.
- Surrender it. You give the car back, and any remaining balance is wiped out.
Our guide on keeping your car in bankruptcy covers each option in more detail.
Can I keep my house?
You can keep your house if two things are true: your equity fits under your homestead exemption, and you’re current on your mortgage. Most Chapter 7 filers keep paying their mortgage without reaffirming it. The lender keeps its lien, so it can foreclose if you stop paying, but you won’t owe the lender anything personally after your discharge.
If you’re behind on your mortgage, Chapter 7 can only delay a foreclosure, not stop it. Chapter 13 lets you catch up on missed payments over three to five years, which is why homeowners who are behind often choose it.
Chapter 7 vs. Chapter 13
| Chapter 7 | Chapter 13 | |
|---|---|---|
| How it works | Wipes out qualifying debt | Repayment plan, then the remaining qualifying debt is wiped out |
| How long it takes | About 3 to 4.5 months | 3 to 5 years |
| Court fee | $338 | $313 |
| Who qualifies | Income under the state median or passes the means test | Regular income and debts under the Chapter 13 limits |
| Your property | Nonexempt property can be sold | You keep your property but pay at least its nonexempt value through the plan |
| Behind on your mortgage or car | Can’t catch up through the case | Can catch up over the plan |
| On your credit report | Up to 10 years from filing | 7 years from filing |
If you pass the means test, have little nonexempt property and are current on anything you want to keep, Chapter 7 is usually the better fit. If you’re behind on your house, have valuable nonexempt property or earn too much for Chapter 7, look at Chapter 13.
Alternatives to Chapter 7
Bankruptcy is a powerful tool, but sometimes it’s more than you need. Before you file, compare your options honestly.
| Option | Best if | Credit impact |
|---|---|---|
| Debt consolidation loan | Your credit is still fair or better and you can afford one lower payment | Small, and it can help over time |
| Debt management plan | You can repay in full over three to five years if a nonprofit counselor lowers your interest rates | Moderate. Your enrolled cards are usually closed |
| Debt settlement | You can save a lump sum and want to avoid bankruptcy, and your debts are mostly credit cards | Significant. Missed payments and settled accounts stay on your report for seven years |
| Chapter 13 | You’re behind on your home or car, or earn too much for Chapter 7 | Significant, 7 years |
| Chapter 7 | You can’t realistically repay your unsecured debt in five years | Significant, up to 10 years |
A simple test: if paying off your unsecured debt in full would take more than five years even on a tight budget, bankruptcy is usually worth a serious look. If you could get there in two or three years with lower interest rates, start with a nonprofit counselor. You can compare credit counseling services or read how debt settlement compares with bankruptcy.
How Chapter 7 affects your credit, and how to rebuild
A Chapter 7 bankruptcy can stay on your credit report for up to 10 years from the date you file. Your score will drop, but if you were already behind on payments, your score was probably taking a beating anyway. Many people see their scores start to recover within a year or two, because their debt-to-income ratio improves overnight. Our guide on how long bankruptcy stays on your credit report explains the timing.
Here’s how to rebuild:
- Check your credit reports after discharge. Every discharged account should show a $0 balance and “discharged in bankruptcy.” Dispute any that don’t.
- Get a secured credit card. Put a small charge on it each month and pay it in full. Our guide to getting a credit card after bankruptcy lists the options.
- Build an emergency fund. Even $500 to $1,000 keeps a surprise car repair from going back on a card.
- Track your progress. The SuperMoney app lets you monitor your credit score, track spending against a budget and watch your net worth climb as you rebuild.
- Plan your mortgage timeline. FHA loans generally require two years after a Chapter 7 discharge, and conventional loans backed by Fannie Mae generally require four.
Frequently asked questions
How long does Chapter 7 take?
Most cases take about three to four and a half months from filing to discharge. The 341 meeting happens 21 to 40 days after you file, and the court usually issues the discharge 60 to 90 days after that.
How much debt do you need to file Chapter 7?
There’s no minimum. What matters is whether you can realistically repay what you owe. People file with $15,000 of debt and with $150,000. If the payments are crushing you and your income is below the median, it’s worth a consultation.
Is it hard to get approved for Chapter 7?
Not if your income is below your state’s median and you fill out your forms completely and honestly. Most cases that run into trouble do so because of missing paperwork, unlisted assets or income above the median.
What do you lose when you file Chapter 7?
Most filers lose nothing but their dischargeable debt. You can lose property that’s worth more than your exemptions, like a second car, a paid-off boat, significant home equity or a large cash balance. Your tax refund for the year you file can also be at risk if it isn’t covered by an exemption.
Can I file Chapter 7 online?
You can prepare your forms online and take both required courses online. Most courts only accept electronic filing from attorneys, so if you file on your own you’ll usually file paper forms at the clerk’s office or by mail, though some courts accept forms through an online upload tool.
How often can you file Chapter 7?
You can get a Chapter 7 discharge once every eight years, measured from filing date to filing date. If your earlier case was a Chapter 13 that ended in a discharge, the wait is generally six years.
Will my employer find out?
Probably not. Bankruptcy filings are public records, but courts don’t notify employers unless your employer is a creditor or the court orders a wage deduction. It’s illegal for a private employer to fire you just because you filed bankruptcy.
Key takeaways
- Chapter 7 wipes out most unsecured debt in about three to four and a half months, and the court fee is $338, with installment and waiver options.
- You qualify if your income is at or below your state’s median, or if you pass the disposable income test.
- More than 95% of Chapter 7 cases are no-asset cases, because exemptions protect what most filers own.
- Child support, alimony, recent taxes and most student loans survive, and liens on your house and car stay in place.
- It stays on your credit report for up to 10 years, but many filers start rebuilding within a year.
Table of Contents