Andrew Latham
Andrew is the Content Director for SuperMoney, a Certified Financial Planner®, and a Certified Personal Finance Counselor. He loves to geek out on financial data and translate it into actionable insights everyone can understand. His work is often cited by major publications and institutions, such as Forbes, U.S. News, Fox Business, SFGate, Realtor, Deloitte, and Business Insider.
articles from Andrew
1346 posts
Home Equity Loan vs Personal Line of Credit: Which Fits Your Needs?
Published 10/01/2025 by Andrew Latham
A home equity loan (HEL) gives you a lump sum at a fixed rate and uses your home as collateral. A personal line of credit (PLOC) is typically unsecured, offers flexible access to funds, and usually has a variable rate. Choose a HEL if you want predictable payments and the lowest per-dollar cost; choose a PLOC if you value flexibility and don’t want to pledge your home.
Home Equity Loan vs Cash-Out Refinance: Which Is Better for You?
Published 10/01/2025 by Andrew Latham
A home equity loan (HEL) adds a second, fixed-rate mortgage on top of your existing one, giving you a lump sum with predictable payments. A cash-out refinance replaces your first mortgage with a new (often larger) one and gives you cash at closing. If your current first-mortgage rate is low, a HEL usually preserves it. If today’s market rate is meaningfully lower than your existing rate—or you want a single payment—cash-out may be better.
Steps in the Home Equity Loan Process: From Application to Funding
Published 10/01/2025 by Andrew Latham
The home equity loan (HEL) process follows clear stages: pre-qualification, application & disclosures, valuation (appraisal/alternative), underwriting, closing, and funding. Most files close in a few weeks when documentation is complete and property valuation is straightforward. You’ll move faster by preparing documents early, responding quickly to lender requests, and keeping your combined loan-to-value (CLTV) within target.
Can You Get a Home Equity Loan Without an Appraisal?
Published 10/01/2025 by Andrew Latham
Yes—some lenders will approve a home equity loan without a full interior appraisal by using alternatives like automated valuation models (AVMs), desktop or drive-by appraisals, or appraisal waivers on low-risk files. Skipping a full appraisal can save time and money, but it may limit how much you can borrow since conservative values are often used.
How Much Home Equity Do You Need for a Loan?
Published 10/01/2025 by Andrew Latham
Most lenders want you to leave at least 15%–20% equity in your home after taking a home equity loan. In practice, that means keeping your combined loan-to-value (CLTV) at or below 80%–85%. Calculate CLTV by dividing all mortgage balances (plus the new HEL) by your home’s current market value.

The Feds Shut Down. You Should Too. (Here’s How a Personal Budget Freeze Helps You)
Published 10/01/2025 by Andrew Latham
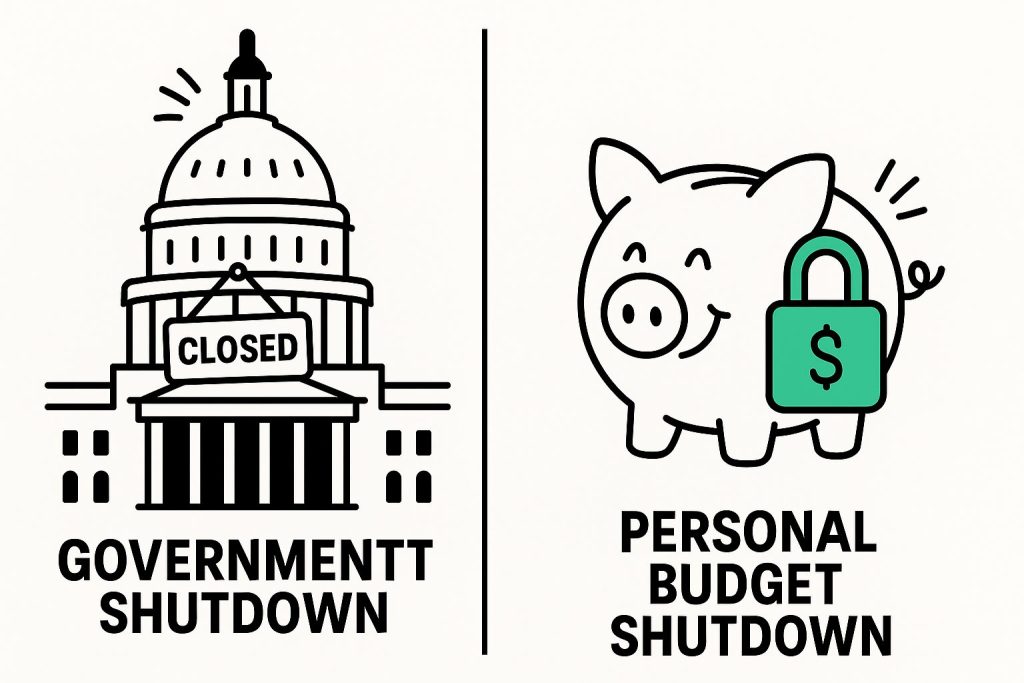
While a government shutdown often signals political dysfunction and economic risk, a personal budget shutdown can have the opposite effect. By temporarily cutting nonessential spending, you can clarify your financial priorities, reduce waste, and reset your budget.
How to Qualify for a Home Equity Loan: Credit, Income & Equity Requirements
Published 10/01/2025 by Andrew Latham
Most lenders look for a mid-600s credit score, a debt-to-income ratio (DTI) at or below ~43% (sometimes up to 50%), steady verifiable income, and enough equity to keep your combined loan-to-value (CLTV) at 80%–85% or lower. Strengthen your application by paying down revolving debt, documenting income clearly, and leaving at least 15%–20% equity after borrowing.
Risks of a Home Equity Loan: What Borrowers Should Watch Out For
Published 09/30/2025 by Andrew Latham
Home equity loans (HELs) are secured by your home, which means missed payments can lead to foreclosure. Other key risks include overborrowing, reduced equity and flexibility, higher total interest over long terms, and the possibility of owing more than your home is worth if values fall. A clear payoff plan, conservative borrowing, and careful lender comparison can greatly reduce these risks.
Home Equity Loan Fees Explained: Origination, Appraisal & More
Published 09/30/2025 by Andrew Latham
Home equity loans come with several fees—most commonly origination, appraisal, title, and recording charges. Expect total fees to vary by lender and market, and note that some are negotiable or can be waived. Comparing lender fee sheets and asking the right questions can save hundreds of dollars.
Home Equity Loan Interest Rates: How They’re Set and What’s Average
Published 09/30/2025 by Andrew Latham
A lender’s offered interest rate is rarely random. It reflects your financial profile and broader economic conditions. Key factors include: